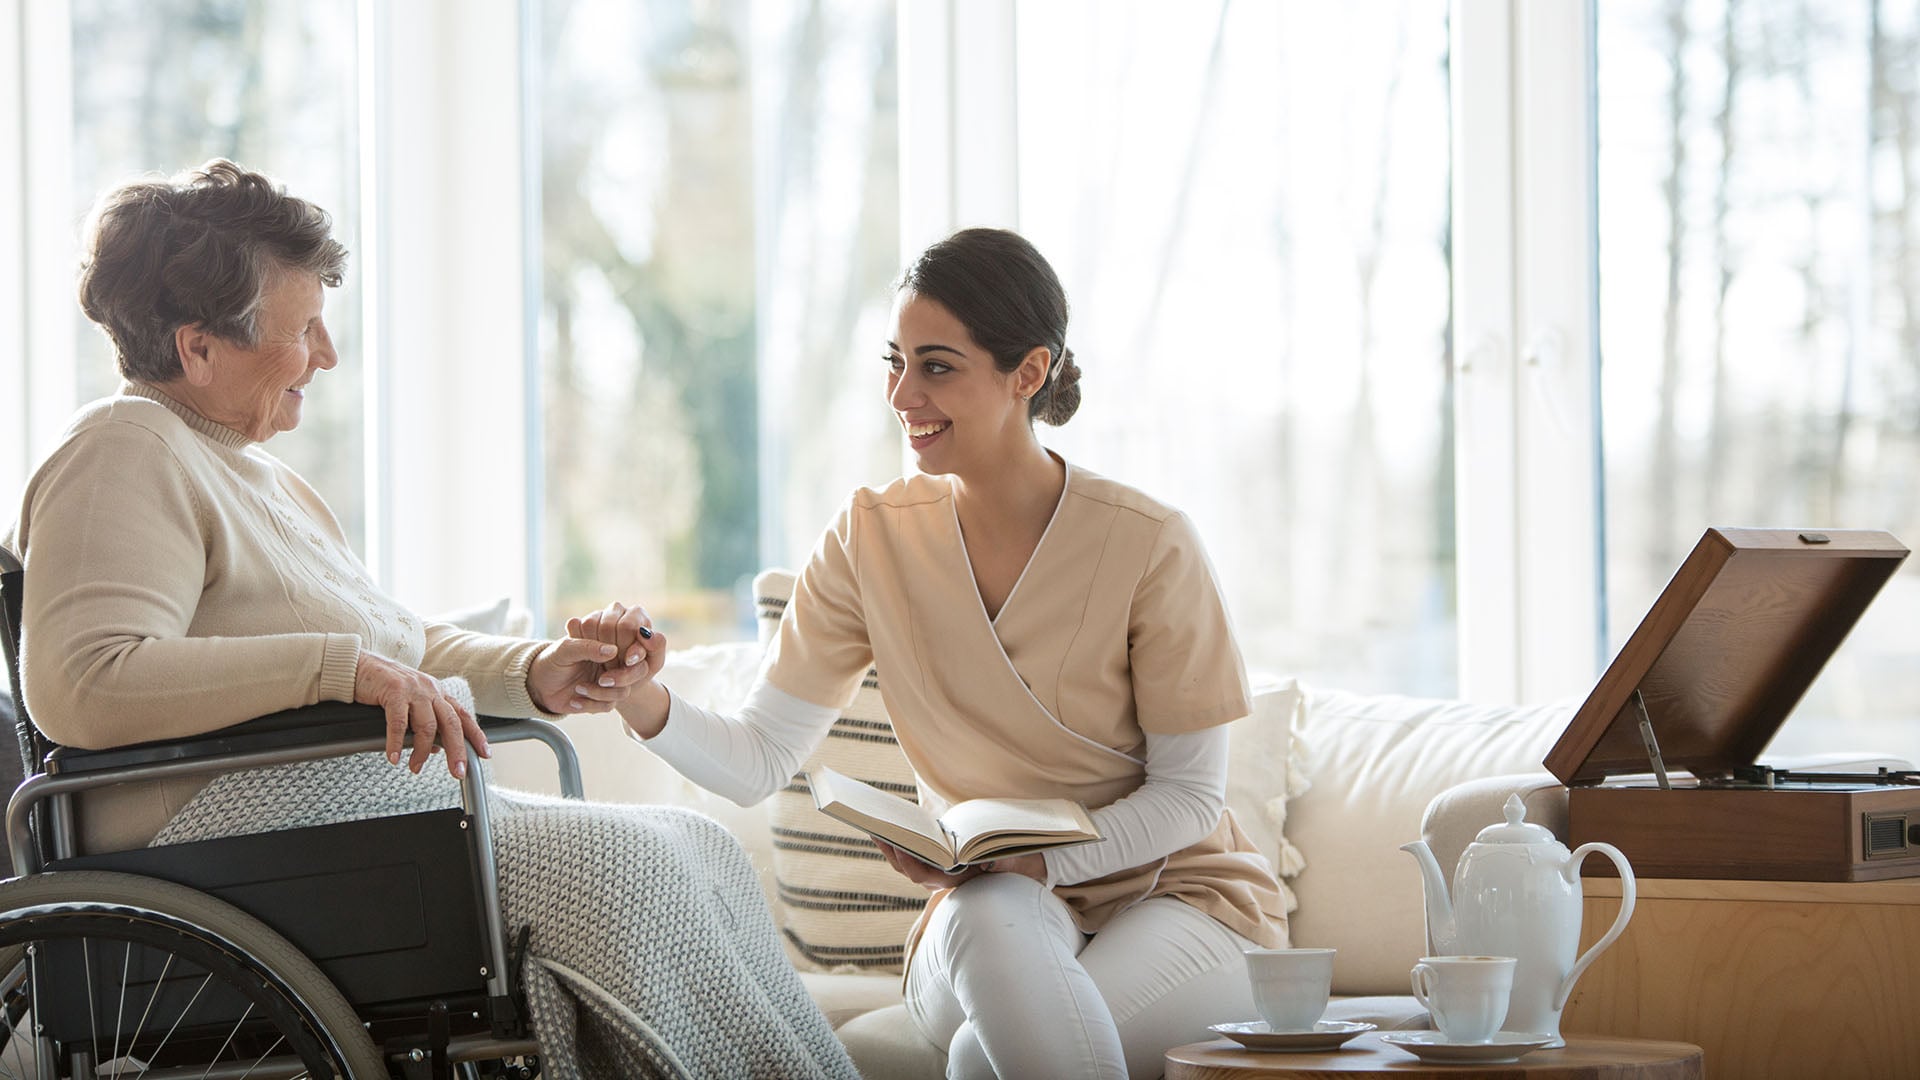
There’s a reason so many patients ask to be treated at home rather than in a hospital room. Think about how you’d want to be cared for. Home offers something a facility can’t: the comfort of familiar surroundings, paired with the reassurance of skilled care close by. That pull toward home-based treatment is reshaping healthcare, and it’s one of the forces behind the growth in home health and hospice.
Home-based care continues to expand as an aging population, evolving care models, and advances in technology allow more patients—including higher-acuity patients—to receive care outside traditional facilities. But growth in home health and hospice has also brought reimbursement pressure, staffing shortages, and shifting regulatory requirements behind home health agencies, hospice providers, and the senior care organizations that surround them. For agents placing these risk types, that means the accounts on your desk are getting more complicated, even when the submission itself looks routine.
Revenue Tells Only Part of the Story
It’s easy to lead with the numbers that underwriters typically ask for first, like revenue, payroll, and headcount. Those figures are important, but they describe an operation’s size, not its exposure.
As Lee Woodruff, Vice President at Jencap put it, “Two accounts with similar revenue can look completely different once you understand what is happening operationally.” Underwriters try to get that operational picture from the first submission onward, and accounts that spell it out clearly tend to move faster than those that leave carriers with unanswered questions.
The Questions Underwriters Are Really Asking
Because a handful of operational details tend to separate a straightforward placement from a difficult one, think about these questions when you’re prepping one of your healthcare clients:
- What is the patient acuity, and what services are provided? A home health agency managing wound care and IV therapy for medically complex patients carries a different exposure than one focused on companion care, even at similar revenue.
- What’s the staffing model? Contract labor, high turnover, and varied levels of clinical training all change the picture. The Bureau of Labor Statistics projects employment of home health and personal care aides to grow 18 percent from 2025 to 2035, with roughly 760,500 openings a year. That kind of churn means the workforce behind an account rarely stays static.
- What’s the care setting and jurisdiction? Home health and hospice aren’t one interchangeable market. The Centers for Medicare and Medicaid Services (CMS) finalized a permanent and temporary adjustment that reduces CY 2026 home health payments by about 1.3 percent, while the FY 2027 hospice final rule increased hospice payment rates by 2.3 percent. Reimbursement is moving in opposite directions for two segments agents sometimes discuss as if they were the same thing.
- What is the loss history? Prior claims tell underwriters more than any narrative summary can, especially when you spell out the operational details behind them.
- What does their loss control strategy look like? Carriers want to see how an operation protects its own employees, not just its patients, particularly around the lifting, transfers, and exposure to infectious materials that drive workers' compensation claims in home-based care. Real investment in safety training and proactive risk mitigation reads very differently to an underwriter than no plan at all.
Unfortunately, none of these variables just “show up” on a declarations page. That would be far too easy. Instead, you’ve got to do a little legwork up front to strengthen your submission by front-loading what you know underwriters will eventually ask for anyway. Answer the questions above, and you’ll be more likely to move swiftly and land with markets that are a genuine fit.
Frequently Asked Questions
What information do underwriters need for home health and hospice insurance?
Underwriters generally want detail on patient acuity, the specific services provided, the staffing model (including contract labor use), the states and settings where care is delivered, and a loss run with context behind the claims.
How does patient acuity affect healthcare insurance underwriting?
Higher acuity patients, such as those receiving IV therapy or complex wound care at home, typically carry more clinical risk than patients receiving companion or custodial care, even when the agencies serving them report similar revenue.
How do staffing models affect healthcare liability insurance?
Underwriters may consider contract labor use, turnover, staff qualifications, training, and supervision because these factors can affect how services are delivered and managed.
Why are some healthcare insurance risks difficult to place?
Accounts become difficult to place when reimbursement pressure, complex service lines, or a thin loss history narrative leave underwriters without enough operational context to price the risk confidently.
What should agents include in a healthcare insurance submission?
A strong submission includes patient population and acuity details, a breakdown of the staffing model, the jurisdictions and settings where services are provided, and current loss runs, along with context around material claims.
Send Us the Hard Ones
Jencap's specialty reach already covers the healthcare landscape end to end, from property and casualty to workers' compensation and professional lines, and everything in between. If you have a home health, hospice, assisted living, or other healthcare account that has been sitting on your desk because the fit isn't obvious, that is exactly the kind of submission our healthcare team works on. Get a quote or find the broker in your region to start the conversation before the account gets harder to place, not after.